
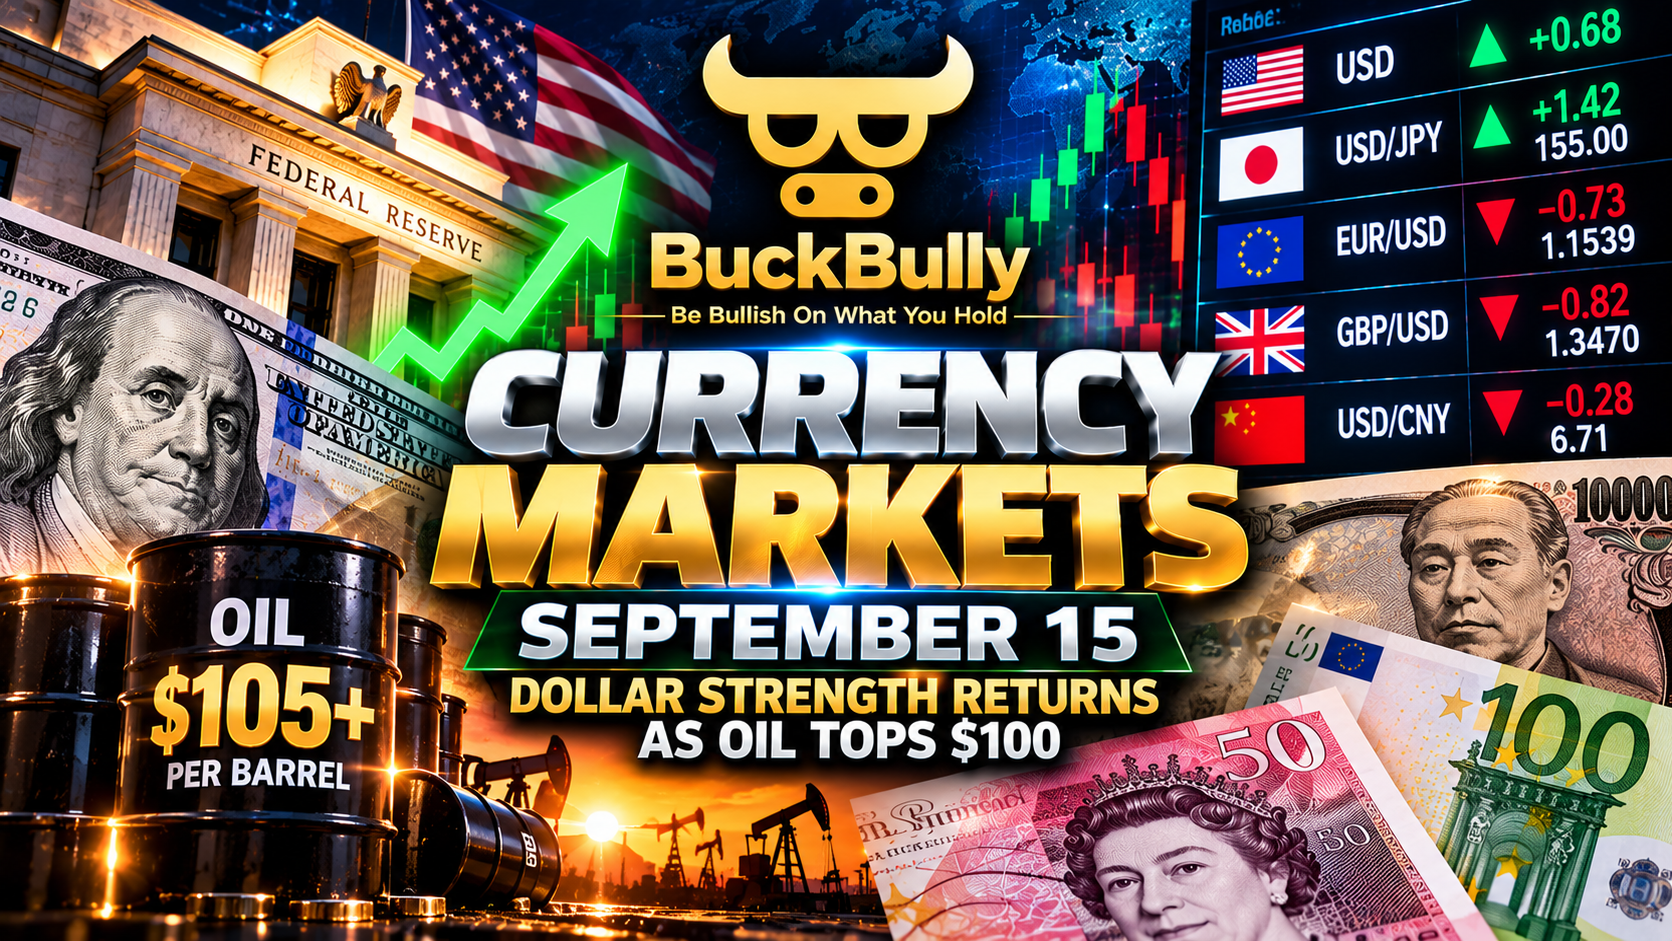
Dollar Strength Returns as Oil Tops $100
The currency market has changed again.
On September 1, the Japanese yen was dangerously close to ¥160 per U.S. dollar. By September 8, the yen had staged a dramatic comeback toward ¥153. Now, on September 15, the dollar is fighting back as oil trades above $105, U.S. Treasury yields reach levels not seen since 2007, and traders prepare for one of the most important Federal Reserve decisions of the year.
The market was pricing a greater than 92% probability of a Federal Reserve rate increase heading into the September 16 decision. At the same time, escalating Middle East tensions pushed oil higher, increasing fears that energy inflation could force central banks to remain aggressive. (MarketScreener)
That combination has produced a familiar result:
Higher oil → higher inflation expectations → higher bond yields → higher rate expectations → stronger U.S. dollar.
September’s currency battle is no longer simply about the yen.
It’s becoming a global interest-rate battle.
💵 U.S. DOLLAR — THE COMEBACK
The dollar regained momentum on September 15 against most major currencies as traders positioned for another Fed hike.
The catalyst wasn’t just the Federal Reserve.
The benchmark 10-year U.S. Treasury yield briefly reached 5.041%, its highest level since 2007. (MarketScreener)
That’s a major development for currencies.
When Treasury yields increase, dollar-denominated assets can become more attractive to global investors. Capital flowing toward those higher yields can increase demand for dollars.
At the same time, oil above $105 is creating renewed inflation pressure.
BuckBully Trend: USD — 📈 BULLISH
The dollar has reclaimed momentum heading into the Fed decision.
But September 16 becomes the real test.
A rate increase is already heavily priced into markets, meaning the bigger currency move could come from what the Fed says about future hikes, rather than the hike itself.
🛢️ OIL ABOVE $105 CHANGES EVERYTHING
Crude oil has become one of the biggest forces driving currencies.
Oil traded above $105 per barrel September 15 after renewed attacks on Saudi Arabia and the postponement of Gulf-Iran negotiations raised concerns about global supplies. (MarketScreener)
Later in the session, prices climbed above $108 as supply concerns intensified. (Reuters)
That’s important because countries experience an oil shock very differently.
For major oil exporters, rising prices can support government revenue and sometimes their currencies.
For major importers, expensive energy can mean:
higher inflation + weaker growth + larger import bills.
That puts currencies including the yen, euro and pound in an uncomfortable position.
🇯🇵 JAPANESE YEN — THE RALLY COOLS
The yen was September’s biggest currency story last week.
USD/JPY collapsed from around 160 toward 153, producing a powerful yen rally.
By September 15, however, the pair was climbing again as U.S. yields and Fed expectations strengthened the dollar.
Using the ECB’s September 15 reference rates—€1 = $1.1539 and €1 = ¥178.86—USD/JPY works out to approximately:
$1 ≈ ¥155.0
(Eur-Lex)
That’s still substantially stronger for the yen than the ¥160 area seen at the beginning of September, but weaker than the levels reached during last week’s dramatic rally.
The September chart now tells an interesting story:
Sept. 1: ~¥160
⬇️
Sept. 8: ~¥153
⬆️
Sept. 15: ~¥155
That’s volatility.
And it demonstrates why currency trends rarely move in straight lines.
BuckBully Trend: JPY — ⚠️ NEUTRAL / VOLATILE
The yen’s September recovery hasn’t disappeared, but the dollar has regained the short-term advantage.
The next battle zone remains roughly ¥155–¥160.
🇪🇺 EURO — FALLING BACK
The euro is beginning to show more obvious weakness.
The ECB’s official September 15 reference rate was:
€1 = $1.1539
(Eur-Lex)
That’s down from approximately $1.1614 on September 8.
The move isn’t enormous, but the direction matters.
The European Central Bank raised borrowing costs the previous week, yet the euro still struggled against the dollar as investors increasingly focused on U.S. yields and energy prices. (Reuters)
Europe is particularly vulnerable to another major energy shock.
Higher oil prices can simultaneously:
increase inflation
while
reducing economic growth.
That puts the ECB in a difficult position.
BuckBully Trend: EUR — 📉 WEAKENING
The $1.15 area becomes an important psychological zone.
A sustained move below that level would make the euro’s September chart considerably more bearish.
🇬🇧 BRITISH POUND — ONE-MONTH LOW
The pound is showing similar pressure.
Sterling traded around:
£1 = $1.347
on September 15, its weakest level in more than a month. (Reuters)
That’s notable because the pound had been surprisingly resilient during the first half of September.
The problem is energy.
Britain is a net oil importer, making the economy particularly vulnerable to higher energy costs.
At the same time, Britain’s labor market has weakened, with wage growth slowing, vacancies declining and hiring falling. (Reuters)
Normally that might encourage the Bank of England to keep rates lower.
But oil-driven inflation is pushing in the opposite direction.
Markets were fully pricing at least one 25-basis-point Bank of England increase before year-end, with a substantial chance of another. (Reuters)
BuckBully Trend: GBP — 📉 SOFT
Sterling hasn’t collapsed, but momentum has clearly weakened.
The Bank of England’s September 17 meeting could become the next catalyst.
🇨🇳 CHINESE YUAN — QUIET WHILE EVERYONE ELSE MOVES
The Chinese yuan remains considerably less dramatic.
ECB reference data for September 15 showed:
€1 = ¥7.7444 Chinese yuan.
Combined with EUR/USD at $1.1539, that implies approximately:
$1 ≈ ¥6.71 CNY
(Eur-Lex)
That relative stability stands out when compared with the violent movements in the Japanese yen.
BuckBully Trend: CNY — ➡️ STABLE
The yuan remains one of the quieter major currencies in a very noisy global FX market.
🇨🇦 CANADIAN DOLLAR — OIL CREATES AN INTERESTING SETUP
The Canadian dollar deserves special attention when crude prices explode.
The ECB’s September 15 reference rates were:
€1 = C$1.6062
and
€1 = $1.1539.
That implies roughly:
$1 ≈ C$1.39
(Eur-Lex)
Canada is one of the world’s major energy producers, meaning higher crude prices can provide an economic tailwind that isn’t available to oil-importing economies.
But the currency isn’t immune to broader dollar strength.
BuckBully Trend: CAD — 👀 WATCH
If oil remains above $100, CAD deserves a spot on the currency watchlist.
🇲🇽 MEXICAN PESO — EMERGING-MARKET TEST
Another currency worth watching is the Mexican peso.
ECB September 15 reference data showed:
€1 = 19.7972 Mexican pesos.
Against the euro’s $1.1539 value, that translates to roughly:
$1 ≈ MX$17.16
(Eur-Lex)
Emerging-market currencies face an important test whenever U.S. yields rise sharply.
Higher Treasury yields can attract global capital toward the United States and away from riskier markets.
If the dollar rally accelerates after the Fed meeting, emerging-market FX could become the next major story.
🌍 CURRENCY BOARD
| Currency | Approx. Sept. 15 Level | Trend |
|---|---|---|
| 🇺🇸 U.S. Dollar | Strengthening broadly | 📈 Bullish |
| 🇯🇵 USD/JPY | ~155.0 | ⚠️ Yen rally cooling |
| 🇪🇺 EUR/USD | 1.1539 | 📉 Weakening |
| 🇬🇧 GBP/USD | ~1.347 | 📉 One-month low |
| 🇨🇳 USD/CNY | ~6.71 | ➡️ Stable |
| 🇨🇦 USD/CAD | ~1.39 | 👀 Oil-sensitive |
| 🇲🇽 USD/MXN | ~17.16 | 👀 Watch U.S. yields |
ECB reference rates provide the cross-rate basis for several figures above; intraday market prices fluctuate continuously. (Eur-Lex)
🔥 SURPRISE MOVE: THE YEN DIDN’T KEEP RUNNING
Last week’s obvious momentum trade was the Japanese yen.
This week provides a reminder of how quickly forex can change.
The yen’s move from roughly 160 toward 153 looked powerful enough to potentially challenge the 150 level.
Instead, USD/JPY rebounded toward 155 as Treasury yields surged and expectations for a Fed increase strengthened.
That doesn’t necessarily invalidate the yen recovery.
It demonstrates something more important:
Interest-rate differentials still matter.
As long as U.S. yields remain dramatically higher than Japanese yields, traders have a financial incentive to hold dollar-denominated assets.
Japan therefore needs more than intervention threats to create a lasting currency reversal.
It needs monetary-policy normalization.
🏦 THE CENTRAL BANK SUPER WEEK
This may be the most important part of the entire September 15 currency setup.
Three major central banks are preparing to make decisions within days of each other.
🇺🇸 Federal Reserve — September 16
Markets entered September 15 pricing a greater than 92% probability of a rate increase. (MarketScreener)
🇬🇧 Bank of England — September 17
The BOE is expected to hold immediately, but markets have increased expectations for additional tightening later in the year as oil raises inflation risks. (Reuters)
🇯🇵 Bank of Japan — September 17–18
Japan remains especially important because expectations for tighter BOJ policy helped produce the yen’s dramatic early-September rally.
Three central banks.
Three currencies.
And potentially three completely different messages.
💵 COLLECTOR WATCH: JAPANESE YEN STILL HAS THE STORY
For physical currency collectors, Japan remains the most interesting storyline of September.
Think about what’s happened in only two weeks:
¥160 → intervention fears → ¥153 → carry-trade unwind → rebound toward ¥155.
That gives Japanese currency a compelling current-events connection.
Collectors interested in the category could focus on:
Older discontinued yen designs
High-grade Japanese banknotes
Older ¥1,000, ¥5,000 and ¥10,000 notes
Commemorative Japanese currency
Notes associated with major redesign periods
The important distinction remains the same:
A currency becoming stronger doesn’t automatically make its banknotes more collectible.
Scarcity, condition, series, historical significance and collector demand determine resale premiums.
🐂 BUCKBULLY BOTTOM LINE
September’s currency market has now produced three different chapters in only two weeks.
September 1: Dollar strong. Yen approaching 160.
September 8: Yen explodes higher. USD/JPY approaches 153.
September 15: Dollar fights back. USD/JPY returns toward 155 while the euro and pound weaken.
And now the biggest event arrives.
The Federal Reserve’s September 16 decision could determine whether the dollar’s comeback becomes a larger trend—or another temporary move.
But there’s another number that may matter just as much:
$105+ oil.
If energy remains this expensive, central banks may have a much harder time defeating inflation.
That means higher rates could last longer.
And if higher rates last longer, currencies will increasingly be separated into two groups:
countries capable of tightening monetary policy—and countries that can’t afford to.
That could define the next stage of the global currency market.
BuckBully Currency Watch:
💵 USD — Strengthening
🇯🇵 JPY — Volatile / Watch 155
🇪🇺 EUR — Weakening
🇬🇧 GBP — Under Pressure
🇨🇳 CNY — Stable
🇨🇦 CAD — Watch Oil
Disclaimer: Currency exchange rates fluctuate continuously. Market observations are for informational and educational purposes only and do not constitute individualized financial or investment advice.