
September is ending almost exactly where it began—with the U.S. dollar dominating the global currency market.
But the forces driving the move have become much stronger.
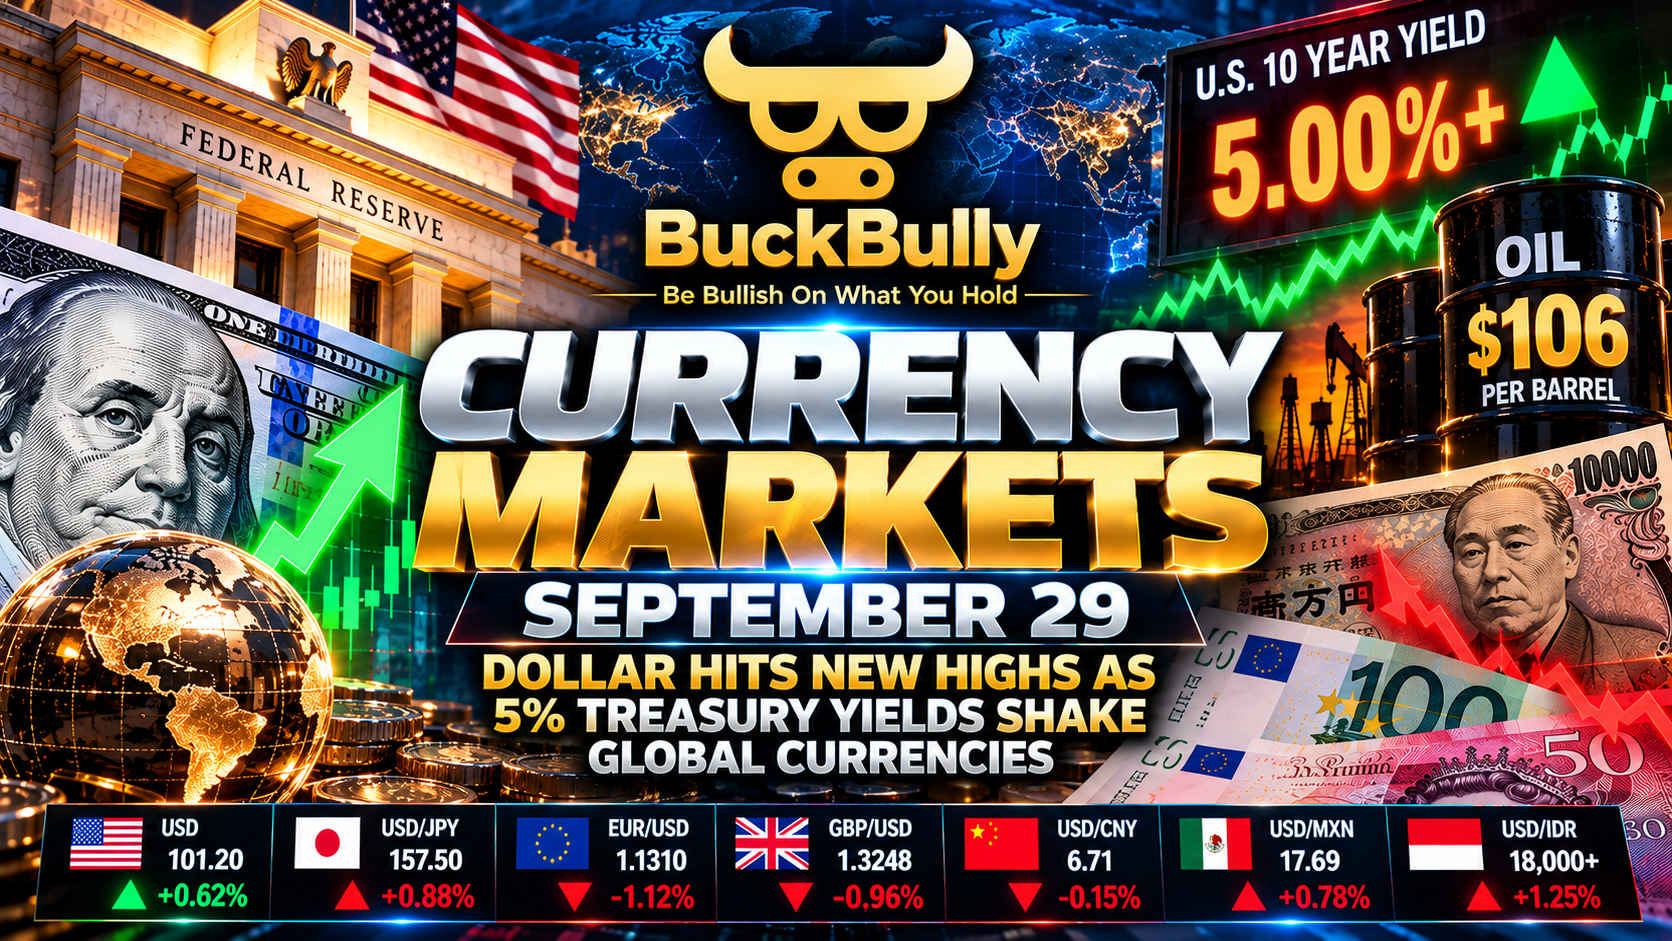
On September 29, the dollar reached a 16-month high against both the euro and Swiss franc, while the U.S. 10-year Treasury yield remained above 5%. The Dollar Index hovered around 101.2, putting it on pace for roughly a 1.8% September gain, its strongest monthly performance since June. (Reuters)
Meanwhile, the euro sank toward $1.13, the British pound approached three-month lows, emerging-market currencies came under pressure, and USD/JPY again threatened the ¥160 area.
September’s lesson has become increasingly clear:
Interest rates are controlling the currency market.
💵 U.S. DOLLAR — SEPTEMBER’S COMEBACK STORY
The dollar’s September chart tells an impressive story.
At the beginning of the month, the Dollar Index was below 100. By September 29, it had climbed to approximately 101.2, near a two-month high. (Investing.com Australia)
The biggest catalyst is U.S. Treasury yields.
The benchmark 10-year Treasury yield moved above 5%, after touching its highest level since June 2007. (MarketScreener)
Think about what that means internationally.
If investors can receive around 5% from a benchmark U.S. government bond, other investments—and other currencies—have to offer increasingly attractive returns to compete for global capital.
That can create a powerful cycle:
Higher Treasury yields → greater demand for U.S. assets → greater demand for dollars → pressure on foreign currencies.
BuckBully Trend: USD — 📈 STRONG
The dollar enters the final days of September with momentum, although upcoming U.S. economic data could quickly alter expectations for additional Federal Reserve tightening. (Reuters)
🇪🇺 EURO — SEPTEMBER’S BIG LOSER
The euro has become one of the clearest victims of renewed dollar strength.
EUR/USD fell as low as approximately:
$1.1312
on September 29.
That was its weakest level against the dollar since May 2025. (MarketScreener)
Look at the progression we’ve tracked throughout September:
Sept. 8: ~$1.161
⬇️
Sept. 15: ~$1.154
⬇️
Sept. 22: ~$1.148
⬇️
Sept. 29: ~$1.131
That’s no longer sideways movement.
That’s a recognizable trend.
Europe has been hit by a difficult combination of higher energy costs, political uncertainty and a widening attraction toward high-yielding U.S. assets. (MarketScreener)
BuckBully Trend: EUR — 📉 BEARISH
The $1.13 area becomes the immediate battleground.
If that support fails decisively, traders will naturally begin paying greater attention to the psychologically important $1.10 level.
🇯🇵 JAPANESE YEN — THE ¥160 DRAMA IS BACK
What a month for the yen.
September started with USD/JPY around 160.
Then came one of the month’s biggest reversals:
160 → 153 → 155 → 157 → 159.
Federal Reserve historical data show USD/JPY reaching approximately 158.92 during the final full week of September, before pulling back somewhat. (Federal Reserve)
The fascinating part is that Japan has already tightened monetary policy.
But higher Japanese rates haven’t been enough to overcome the enormous yield advantage available in the United States.
That leaves the market caught between two powerful forces:
U.S. yield advantage pushing USD/JPY higher
versus
Japanese intervention risk pushing traders away from ¥160.
BuckBully Trend: JPY — ⚠️ WEAK / INTERVENTION WATCH
The closer USD/JPY gets to 160, the more dangerous chasing the move becomes.
We’ve already seen this movie once in September.
🇬🇧 BRITISH POUND — $1.32 BECOMES THE BATTLEGROUND
Sterling hasn’t escaped the dollar rally either.
Federal Reserve data showed the pound moving from approximately $1.337 earlier in the period toward $1.322–$1.325 late in the month. (Federal Reserve)
Reuters also reported sterling near a three-month low around $1.3248 during September 29 trading. (Investing.com Australia)
That’s a meaningful deterioration from levels above $1.35 earlier this month.
BuckBully Trend: GBP — 📉 WEAK
The pound hasn’t experienced the euro’s dramatic breakdown, but the September chart clearly favors the dollar.
The $1.32 region becomes an important area to watch heading into October.
🇦🇺 AUSTRALIAN DOLLAR — RATE HIKE, CURRENCY FALLS
Here’s September 29’s surprise.
The Reserve Bank of Australia raised interest rates—and the Australian dollar still weakened.
That’s similar to what we recently watched happen with Japan.
Reuters reported the Australian dollar declining even after the RBA delivered its expected increase. (MarketScreener)
This illustrates one of the most important concepts in forex:
A rate hike doesn’t automatically make a currency rise.
Markets care about what was already expected.
If everyone expects an increase, traders may have already priced it into the currency before the announcement.
Then attention immediately shifts toward:
What’s next?
If investors believe the Federal Reserve will ultimately be more aggressive than another central bank, the dollar can still outperform even when that foreign central bank raises rates.
🇨🇳 CHINESE YUAN — STILL HOLDING UP
China continues to stand out.
Federal Reserve data put USD/CNY around:
6.71
during the final week of September. (Federal Reserve)
Compare that stability with the enormous moves occurring elsewhere.
The euro has broken down.
The pound is near multi-month lows.
The yen has experienced violent swings.
Several emerging-market currencies are under serious pressure.
Yet the yuan remains comparatively controlled.
BuckBully Trend: CNY — ➡️ STABLE
That doesn’t mean China’s economy is without challenges.
It means the currency itself has avoided the type of disorderly adjustment occurring elsewhere.
🇲🇽 MEXICAN PESO — DOLLAR PRESSURE ARRIVES
The Mexican peso has also weakened as U.S. yields climbed.
Federal Reserve data show USD/MXN moving from approximately 17.23 toward 17.69 during the final part of September. (Federal Reserve)
That’s a meaningful move for a currency that has historically attracted investors through relatively high interest rates.
The bigger question becomes:
What happens to emerging markets if U.S. Treasury yields remain above 5%?
When relatively safe U.S. government securities offer increasingly competitive returns, investors have less incentive to accept additional emerging-market risk.
BuckBully Trend: MXN — 📉 UNDER PRESSURE
The peso becomes another currency worth watching if the Dollar Index continues climbing.
🇮🇩 INDONESIAN RUPIAH — 18,000 BREAKS
One of the most dramatic emerging-market developments came from Indonesia.
The rupiah weakened beyond:
Rp18,000 per U.S. dollar
on September 29 as rising American yields and dollar strength pressured emerging markets. (Jakarta Globe)
This is important beyond Indonesia.
It shows that dollar strength is beginning to move from a major-currency story into an emerging-market story.
That’s where a strong dollar can become considerably more consequential.
Countries and companies carrying dollar-denominated debt effectively face larger obligations when their domestic currencies weaken.
🛢️ OIL REFUSES TO LEAVE THE CURRENCY STORY
Oil has been one of September’s wild cards.
Early September: rising.
Mid-September: above $105.
September 22: briefly below $100.
September 29: Brent returned to roughly:
$106 per barrel
as markets remained skeptical that diplomatic efforts would quickly resolve the Iran conflict. (Investing.com Australia)
That matters because expensive energy reinforces inflation.
And inflation reinforces the argument for higher interest rates.
Which brings us right back to the dollar.
Oil ↑ → Inflation risk ↑ → Bond yields ↑ → Rate expectations ↑ → Dollar ↑
That chain has repeatedly appeared throughout September.
📊 CURRENCY BOARD
| Currency | Approx. Sept. 29 Level | BuckBully Trend |
|---|---|---|
| 🇺🇸 Dollar Index | ~101.2 | 📈 Strong |
| 🇯🇵 USD/JPY | ~157–159 | ⚠️ Yen weak |
| 🇪🇺 EUR/USD | ~$1.131 | 📉 Bearish |
| 🇬🇧 GBP/USD | ~$1.325 | 📉 Weak |
| 🇨🇳 USD/CNY | ~6.71 | ➡️ Stable |
| 🇲🇽 USD/MXN | ~17.7 | 📉 Peso weakening |
| 🇮🇩 USD/IDR | 18,000+ | 🚨 Rupiah weak |
| 🛢️ Brent Oil | ~$106 | 🔥 Elevated |
These figures represent market snapshots around September 29 rather than fixed exchange rates. (Investing.com Australia)
🔥 SURPRISE MOVE: 5% TREASURY YIELDS
The biggest currency story may not actually be a currency.
It’s the U.S. Treasury market.
The 10-year yield moving above 5% and reaching levels last seen around 2007 changes the investment equation globally. (MarketScreener)
A global investor can now compare:
U.S. Treasuries yielding around 5%
against stocks, corporate bonds, foreign government debt, emerging markets, precious metals and other assets.
That’s a very different environment from the ultra-low-rate era.
And currencies are adjusting accordingly.
💵 SEPTEMBER REPORT CARD
Now that we’ve tracked the currency market each week, the month’s progression tells the story better than any single chart.
| Date | Dollar | Yen | Euro | Main Story |
|---|---|---|---|---|
| Sept. 1 | 📈 Strong | 📉 Near ¥160 | ➡️ ~$1.16 | Fed expectations |
| Sept. 8 | 📉 Softer | 🔥 Near ¥153 | ➡️ ~$1.16 | Yen short squeeze |
| Sept. 15 | 📈 Rebounding | ⚠️ ~¥155 | 📉 ~$1.154 | Oil + Fed |
| Sept. 22 | 📈 Strong | 📉 ~¥157 | 📉 ~$1.148 | Central-bank divergence |
| Sept. 29 | 🔥 Strongest | 📉 ~¥157–159 | 🚨 ~$1.131 | 5% Treasury yields |
The winner of September’s price action has clearly been the U.S. dollar, while the euro experienced one of the more significant deteriorations among major currencies. The yen gets the award for most volatile—moving from intervention territory to a dramatic rally and almost all the way back again. (Investing.com Australia)
💰 BUCKBULLY COLLECTOR WATCH
From the physical-currency perspective, September created several interesting themes.
Japanese yen remains the headline collectible story. Its extraordinary month provides a natural conversation starter for older Japanese banknotes and discontinued designs.
European currency deserves attention. A weakening euro doesn’t automatically increase collectible value, but older pre-euro notes from Germany, France, Italy, Spain and other eurozone countries remain fundamentally different collectibles because those national currencies no longer circulate.
Emerging-market notes are becoming more interesting. Indonesia crossing 18,000 rupiah per dollar is exactly the type of monetary event that can bring attention to high-denomination foreign banknotes. (Jakarta Globe)
But the BuckBully rule remains:
Don’t buy a banknote simply because its currency is weak.
For resale, prioritize:
scarcity + condition + discontinued series + historical importance + unusual denominations + collector demand.
A currency can lose 50% of its exchange value while a scarce note denominated in that currency increases substantially in collectible value.
🐂 BUCKBULLY BOTTOM LINE
September started with the dollar strong.
Then the yen shocked everybody.
Then oil exploded.
Then central banks raised rates.
And now the dollar is finishing the month near its strongest levels.
The most important chart heading into October may not be USD/JPY or EUR/USD.
It’s the U.S. 10-year Treasury yield.
As long as American yields remain near or above 5%, the dollar has a powerful source of support.
But there’s already a potential twist developing.
Later on September 29, Federal Reserve policymaker John Williams pushed back against expectations for aggressive additional tightening, helping pull the two-year Treasury yield lower and causing investors to reduce some rate-hike bets. (Reuters)
That means October could begin with another reversal.
And after watching September produce:
Dollar → Yen → Dollar → Dollar
currency investors should probably expect one thing above everything else:
Volatility isn’t finished.
BuckBully October Watch: 💵 USD — Strong | 🇯🇵 JPY — Intervention Risk | 🇪🇺 EUR — Under Pressure | 🇬🇧 GBP — Weak | 🇨🇳 CNY — Stable | 🇲🇽 MXN — Watch Yields | 🇮🇩 IDR — High Risk
Disclaimer: Currency exchange rates fluctuate continuously. This article is for informational and educational purposes only and does not constitute individualized financial or investment advice.